
Forums
Back
Portfolio Management - Sharpe Model
AFM
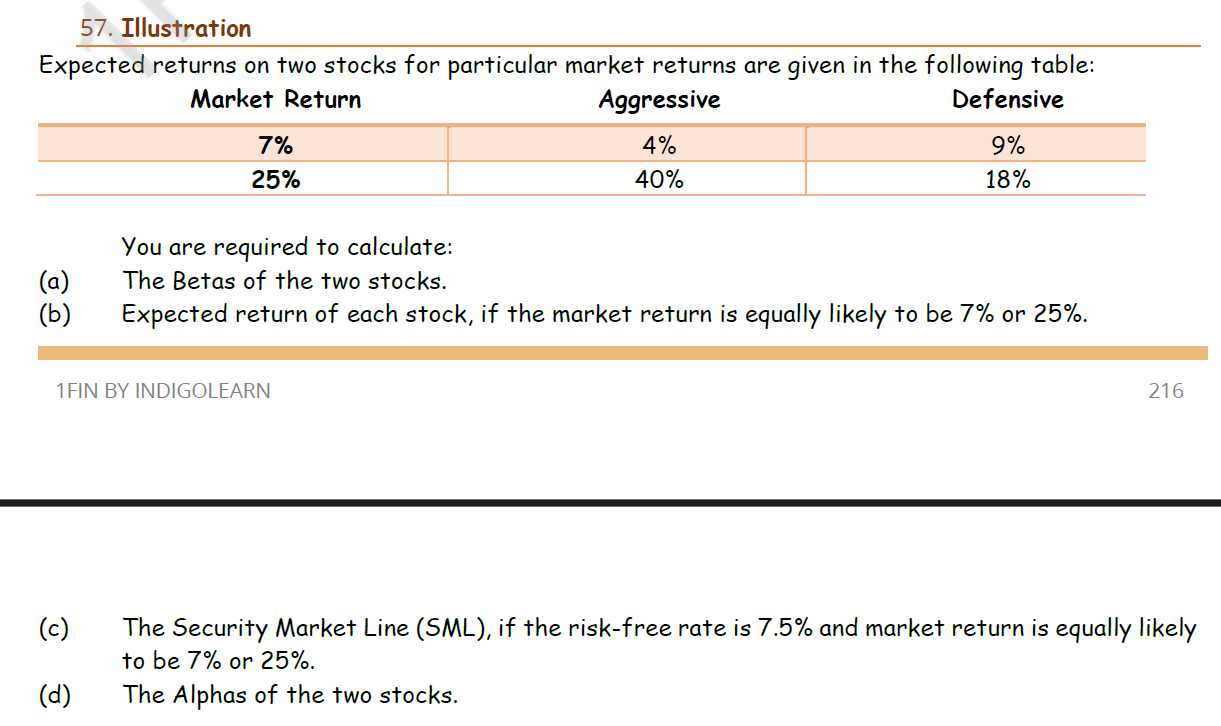
Hello Sir, A general question, In this problem, the 4th part mentions the alpha, If the 4th question was not given, there is no clue we have to use sharpe model right? Or is there any? How to figure out we have to use sharpe model for finding beta and not other formulae Video Details ------------- Advanced Financial Management - AFM Portfolio Management #92. Illustration # 57 - SML & CAPM
Answers (4)
Best Answer
Thread Starter
Susee ArunachalamBefore reading the 4th part, I accidentally used Beta under regression method, But the answer was wrong.
With only two data points we should never use regression or correlation formulae
Sriram Somayajula Admin
In given scenario which other formula will you use other than Sharpe model
Before reading the 4th part, I accidentally used Beta under regression method, But the answer was wrong.
Sriram Somayajula Admin
With only two data points we should never use regression or correlation formulae
Okay sir, understood. Thank you so much sir
Your Reply