
Forums
Back
Portfolio
AFM
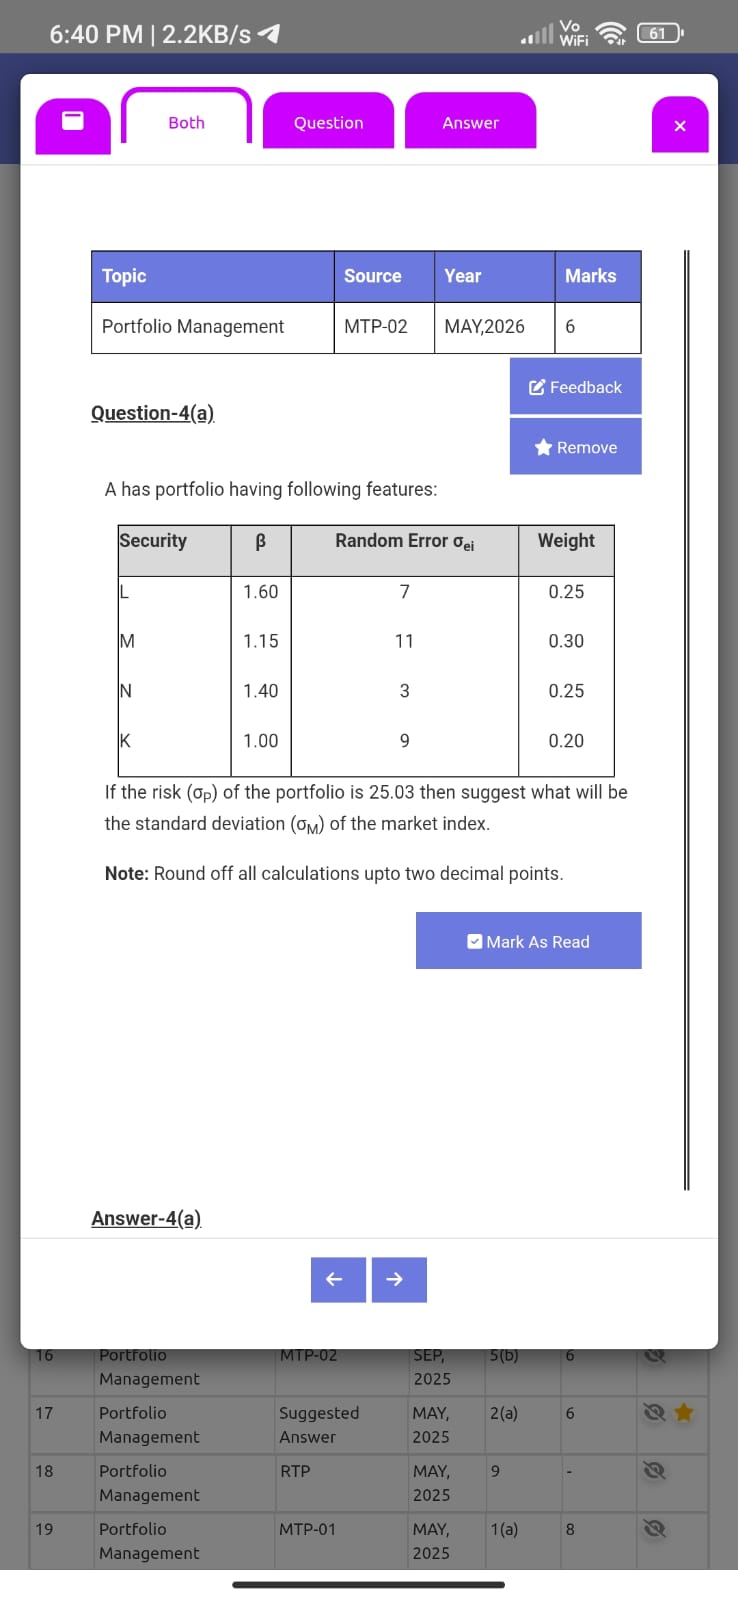
My steps to solve it 1. Calculate unsysyemetic risk 2.find systementic risk=total risk -unsystemetic risk 3.sysemtic risk= beta of portfolio sq.-std.deviatiom of market sq. And from this we get std.dev of market index... But in answer they calculate variance of sh. Individualy....why above method is not right ?

Answers (1)
Your Reply