
Forums
Back
SA 701-Determining key audit matters
Auditing
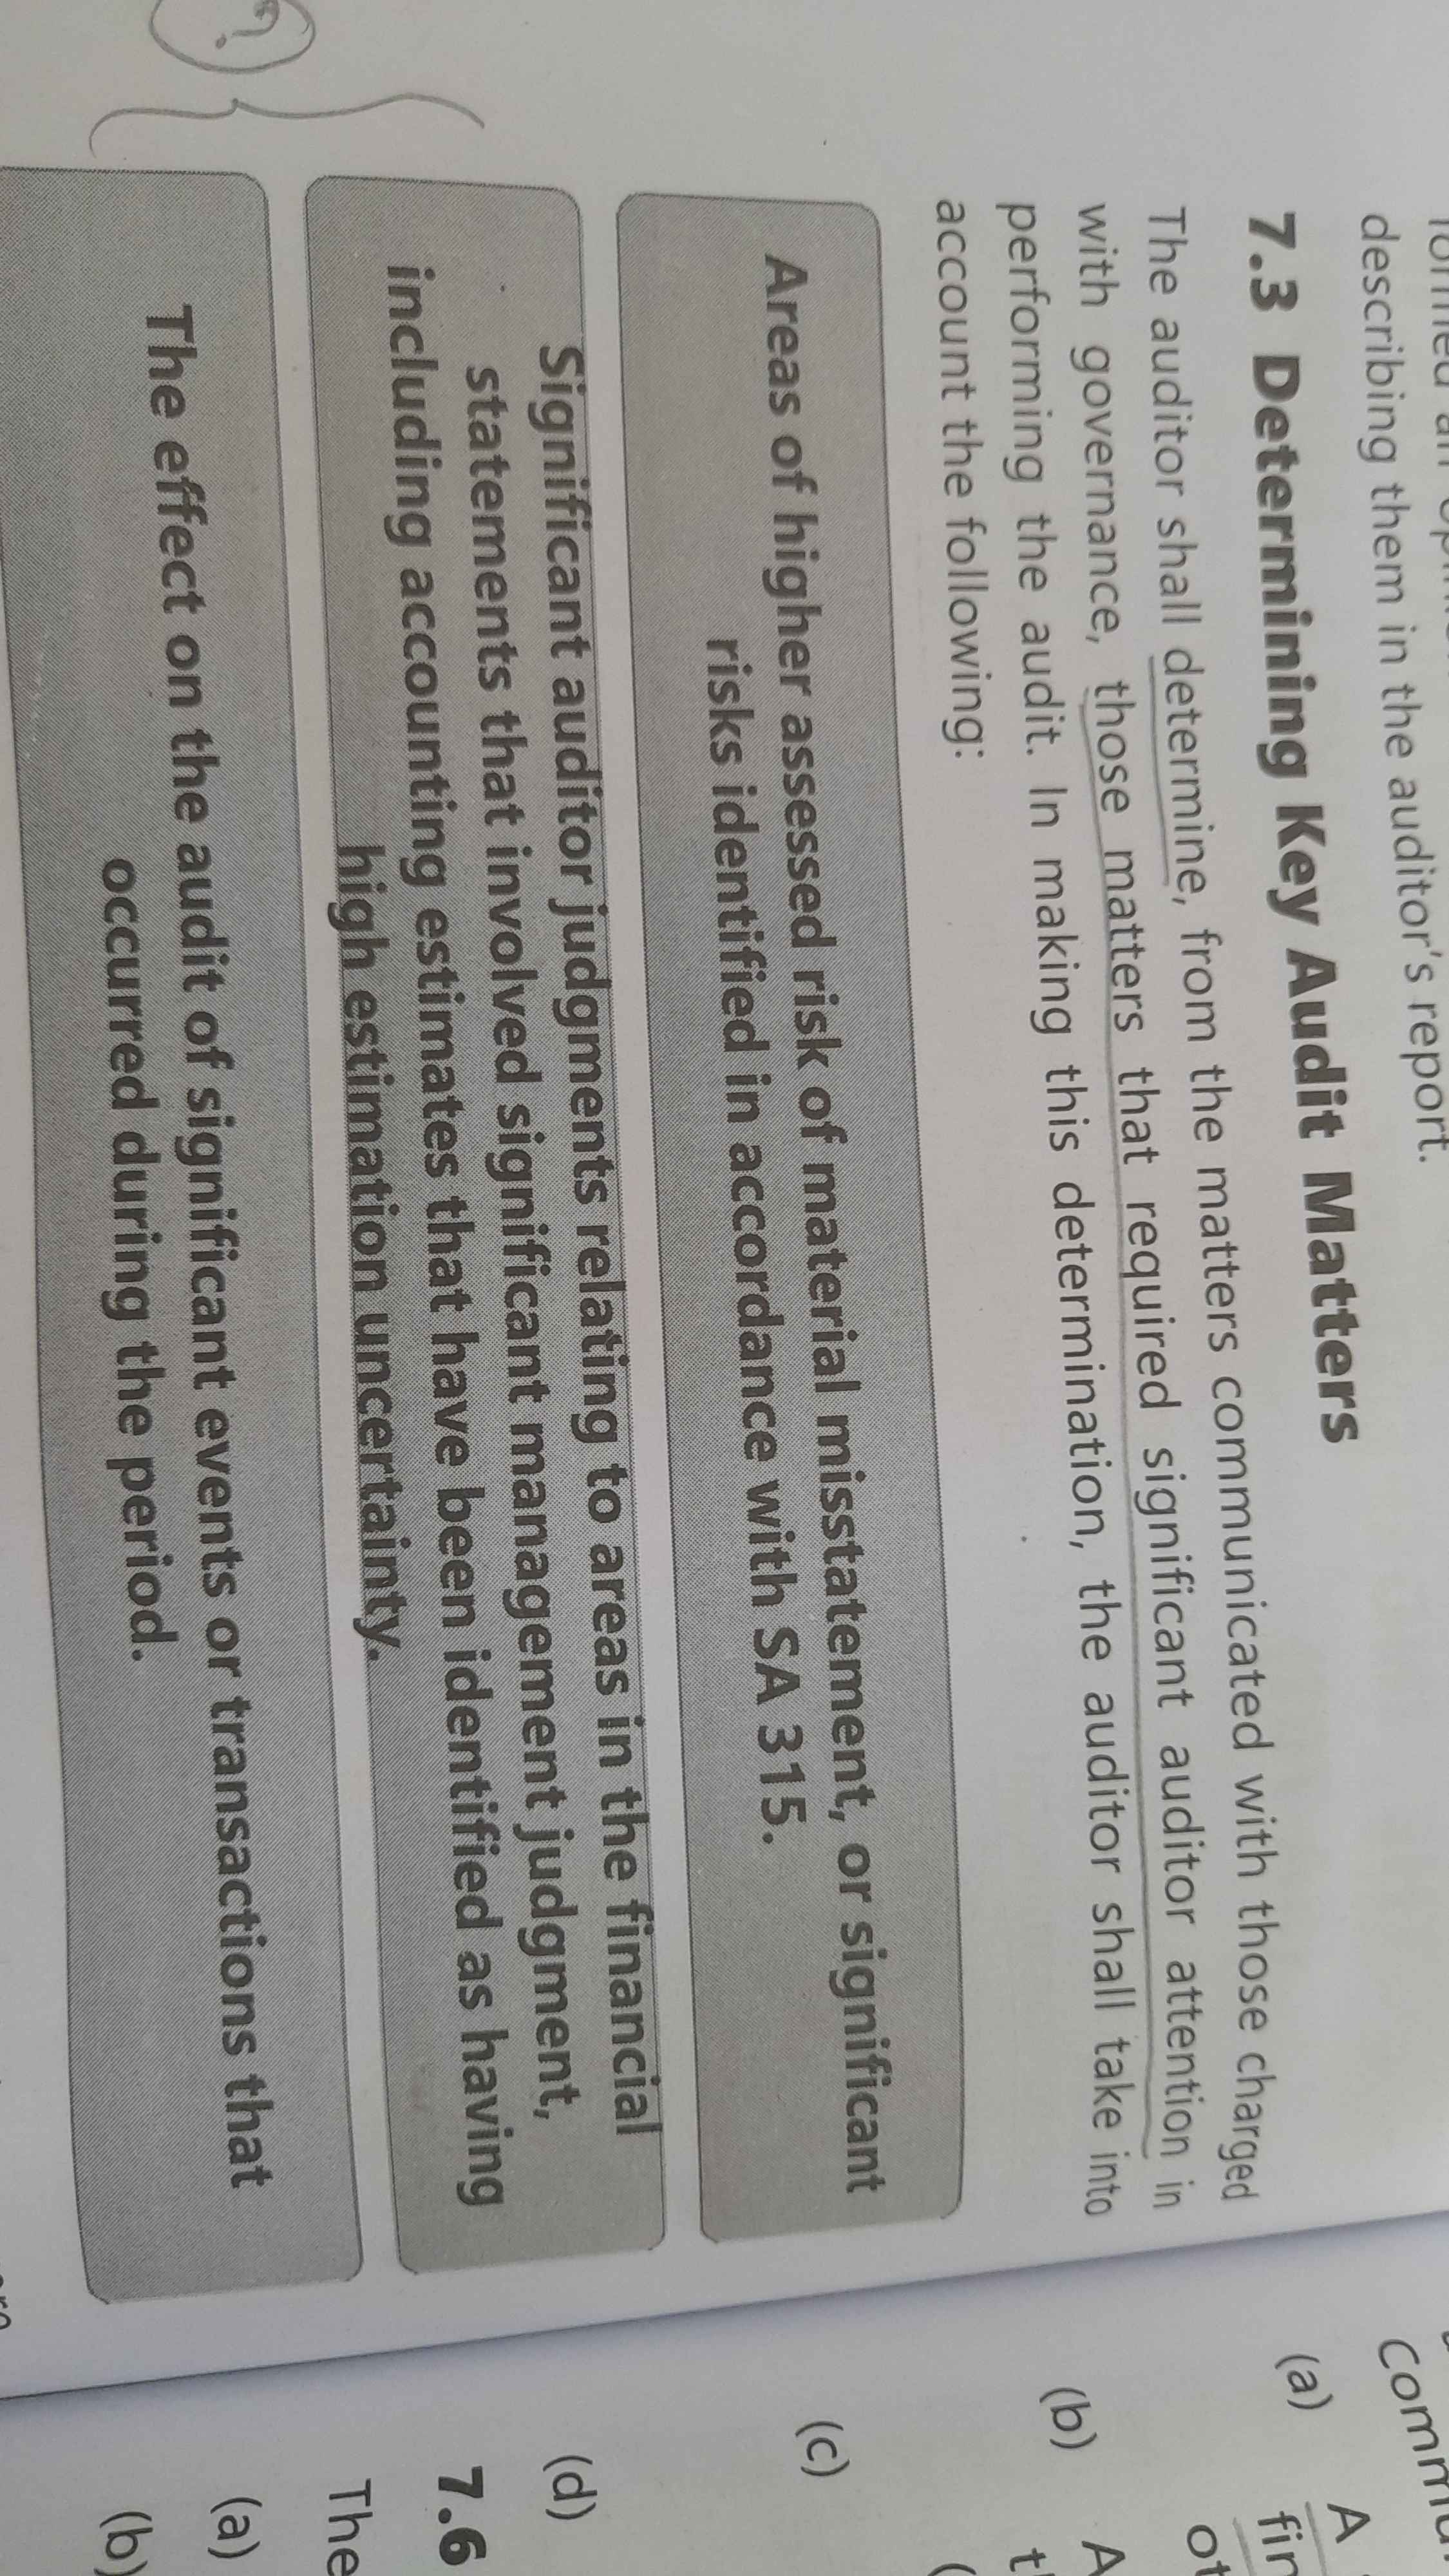
Explain those 2 points with an example.

Answers (1)
Objective of SA 315 is to identify and asses risks of material misstatements. Out of total identified risk areas, few could be highly risky. Such higher risks of material misstatements shall be considered for determining Key audit matters under SA-701. For example auditor has identified 10 areas of risks of material misstatements, and 2 out of 10 are identified high risky then such 2 shall be considered for KAM. Similarly few items of financial statements are based on managements judgements or estimates. And auditor may identify few management judgments are having high estimation uncertainty, such identified areas should also be considered for determining KAM

Your Reply